


Introduction
2025 was yet another strong year for markets, although it wasn’t without volatility, particularly in the first half of the year. As we enter 2026, we are optimistic for broad market performance and are particularly excited about the pockets of the market we are actively allocated to. We believe active management will play a crucial role this year as returns broaden and diverge across asset classes. A combination of macroeconomic drivers, including massive capital expenditures on Artificial Intelligence, easier monetary policy from the Federal Reserve, deregulation, favorable tax policy, and strong earnings growth amid a stable economy, drives our bullish thesis. In this edition of our 2026 Outlook, we will cover:
- 2025 Wrapped – A Lookback on Reality vs. Expectations
- The AI Revolution – A One-Size-Does-Not-Fit-All Megatrend
- Monetary Policy – The Fed’s Next Moves
- Beyond the Fed and AI – What Could Help Move Markets?
- Market Breadth – Returns Beyond the Magnificent 7
- Beyond AI – Sectors for 2026
- Risks to our Outlook – What could go wrong?
We hope you enjoy our outlook for markets in 2026. Looking for additional analysis? See our insights page, podcasts, and weekly market notes emails for more information.
2025 Wrapped – A Lookback on Last Year’s Outlook
As any good analyst team should do, we reviewed our 2025 Outlook for consistency and to learn from any misestimates. We were pleased to see that our analysis was relatively in line with reality. A few confirmations of note:
- Confirmation 1: Market valuation did not hinder returns in 2025
We noted that the start-of-year 22x price-to-earnings (P/E) multiple wasn’t a major concern or headwind to markets given the growth prospects. The market now trades at a roughly 23x P/E. Heading into 2026, we don’t believe multiples will provide a major headwind either. Earnings growth rather than multiple expansion is likely to drive market performance this year.
- Confirmation 2: The Fed followed its playbook
We expected inflation to remain tame and allow the Fed to follow its expectation for rate cuts in 2025. We saw three cuts in 2025 and expect the downward trend in rates to continue in 2026.
- Confirmation 3: Our sector picks performed well
We highlighted Tech, Industrials, Utilities, and Financials in our 2025 Outlook. These all performed in the top half of sectors for 2025.
Now for a couple of surprises:
- Surprise 1: Early tariffs were far more extreme
We expected very targeted and specific tariffs heading into 2025. In reality, the first iteration of tariffs was sweeping and severe. Tariffs have since been tempered, but the tariff agenda shocked us, as it did most on Wall Street back in April.
- Surprise 2: Crypto performance underwhelmed
Crypto adoption continued to surge in 2025, but its performance did not, with most cryptocurrencies slightly down on the year. Poor liquidity conditions and cascading leverage liquidations reared an ugly head in ’25, which led to worse performance than expected. We expect performance to improve in ’26 as adoption continues and leverage is utilized more appropriately.
The AI Supercycle
The AI cycle kicked into high gear in mid-2023, and after hundreds of billions of dollars invested, we’re certainly past the first couple of innings. That leads many to speculate “where are we?” in the AI Supercycle. Recently, we have seen this question play out, with investors arguing over whether it’s in the “late innings” or still the “early days”; for several reasons, we’re inclined towards the latter.
- AI investment continues to grow – companies continue to pour hundreds of billions of dollars per year into new AI solutions. While investment without return isn’t enough to propel the market on its own, companies are confident enough in a future payoff to continue piling dollars into the tech.
- AI monetization is beginning – Something that many investors have been waiting for is finally beginning – the monetization of AI tools. To fund large investments, it’s important that companies find ways to generate cash flow from their current products. Increasingly, this means enterprise-scale contracts for company-specific chatbots and data services, and integrating shopping options into free-to-consumer versions of LLMs (Large Language Models).
- AI advancements – It is important to look beyond LLMs when considering the impact or commercial viability of AI. While these tools brought AI to the masses, AI exists in many other facets with huge economic importance. Advancements in driverless vehicles, robotics (both humanoid and industrial), and related industries can unlock significant economic potential.
As long as investment and return on that investment are realized, the industry can continue its rapid growth. Investment has far outpaced returns so far, but as in all things, investment must precede return.
With record levels of AI capex, Hyperscalers continue pouring money into data centers. While this growth-mindset is expected to drive returns in the future, the current monetization of LLMs is severely lagging the upfront expenses these companies incur. Much as we noted with chip makers in the early days of the AI expansion, in the midcycle of AI investment, we’re increasingly focused on the “Picks and Shovels” of the broader AI market. This still includes those chipmakers but has expanded to encompass many of the inputs needed for the datacenter buildout, particularly companies linked to power generation, and the raw materials needed to build it.
Power Generation
Whereas in the earliest days of the AI boom, companies competed to get their hands on any and every available advanced GPU, the current environment has corporations fighting for every available gigawatt of electricity generation.

Unlike most traditional power requirements (people and industrial equipment that require power only during working hours), AI requires 24/7, consistent power. In the United States, two sources are truly capable of delivering that power: Natural Gas and Nuclear. Coal is popular in China, but mostly because it has ample coal reserves, little other domestically produced energy, and weak environmental regulations.
- Nuclear – through industry and political efforts to streamline nuclear development, we anticipate increased full-scale and SMR (Small Modular Reactor) deployment, although the timelines range from a few years to a decade. The first SMRs are expected to come online in the US around 2028, but commercial-scale deployment will take several more years.
- Natural Gas – Natural gas is an easy solution to many data centers’ power needs; it is inexpensive, quick to deploy, and simple to build. It provides 24/7 consistent base-load power and is relatively clean. For these reasons, it has been a popular choice for baseload power and backup generation. Due to international demand and limited supply, utility-scale turbines are now on a several-year backorder.
Raw Materials
AI has driven demand for several industrial metals and other commodities, but especially for uranium and copper.
Uranium is already experiencing new demand from domestic reactor restarts and foreign reactor constructions, and this demand is expected to grow as more domestic reactors come online. A few major producers primarily control uranium supply. Most global uranium is mined in Kazakhstan and refined in Russia, although the West currently meets its needs through Canadian mining and refining capacity, which accounts for a significant minority of the global share. Due to limited global production and the long lead times needed to start new mines, we, along with most industry analysts, expect the supply crunch that pushed uranium spot prices* over $100/lb. to worsen in the coming years.
*Spot prices for uranium are not the best measure of true “price”. Spot pricing generally tracks long-term supply pricing except for in times of market stress. The large majority of global uranium is negotiated privately, on long-term, private deals.
Copper faces similar supply issues to Uranium – relatively (albeit less) concentrated global supply and long lead times to open new mines – but the demand picture is significantly different. The need for more copper is already here and only growing. We’ll discuss the following demand drivers: Electricity generation & transmission, data center cabling, defense, and global economic activity.
- Electricity Generation & Transmission – As noted above, electricity generation has become a major bottleneck in the expansion of AI, and generation is heavily reliant on the use of copper. Traditional power generation methods require about 1 ton of copper per megawatt of electricity, with wind and solar requiring 5-8x as much. In generation alone, many estimates suggest we need about 68 gigawatts over the next 3 years, which equates to 68,000 additional tons of copper (assuming all power is from natural gas). This doesn’t include the need for additional investments in substations and the thousands of miles of transmission lines needed to expand and replace our aging electric infrastructure.
- Data Center Demand– Copper demand driven directly from data centers is Typical Data Centers can use ~10,000 tons of copper, but AI-focused data centers use about 5 times that amount (per Copper.org). While developers are increasing their usage of fiber-optic cables where copper was previously used, copper is still becoming more important in data centers, not less.
- Defense – Copper and copper alloys are used extensively in defense applications, and with heightened spending in the US and Europe, securing a steady supply is important. The US recently added copper to its list of Critical Minerals in 2025, for both economic and defensive reasons.
- Global Economy – One of the largest question marks in copper’s future is that of global economic activity, namely the Chinese economy. While all of the above reasons are large drivers of incremental copper consumption, the Chinese economy uses a significant portion of the copper supply to build homes and various other products. With the real estate sector in China facing significant hurdles, a decline in building activity could be detrimental to future copper prices.
What’s Next for the Fed?
The Federal Reserve dominated much of the stock market news coverage in 2025, and we don’t expect that to change much in 2026. The timing and extent of further rate cuts are likely to be highly data-dependent this year, meaning the Fed will pay close attention to inflation and employment figures when making its rate decisions. Lately, the focus has remained on the job market, with the Fed more apt to lower rates to support employment than keep rates elevated to fight inflation. As we’ve mentioned in recent commentary, we expect lower housing costs to push inflation down further this year, helping the Fed maintain a dovish (easier monetary policy) tilt in its decisions.
Wall Street investors currently expect roughly one to three 0.25% cuts this year. We lean slightly dovish, expecting two to three cuts from the Fed. As a reminder, the current Fed target is 350-375 basis points (3.5%-3.75%).

Regardless of the timing of interest rate cuts, the broader downward trajectory in interest rates should help support and propel the stock market in 2026. Easier monetary policy encourages borrowing, hiring, and wage growth. More dollars flowing throughout the economy traditionally leads to higher asset prices. Once again, the Fed should be a positive force for the market, but we can certainly expect volatility around meeting dates as the Fed debates further policy changes.
Earnings Growth, Buybacks, and Deregulation
There are more reasons to be excited about this market beyond the tailwinds driven by Federal Reserve actions and the AI Supercycle. Namely, strong earnings growth, stock buybacks, and deregulation should support asset prices in 2026.
Earnings Growth
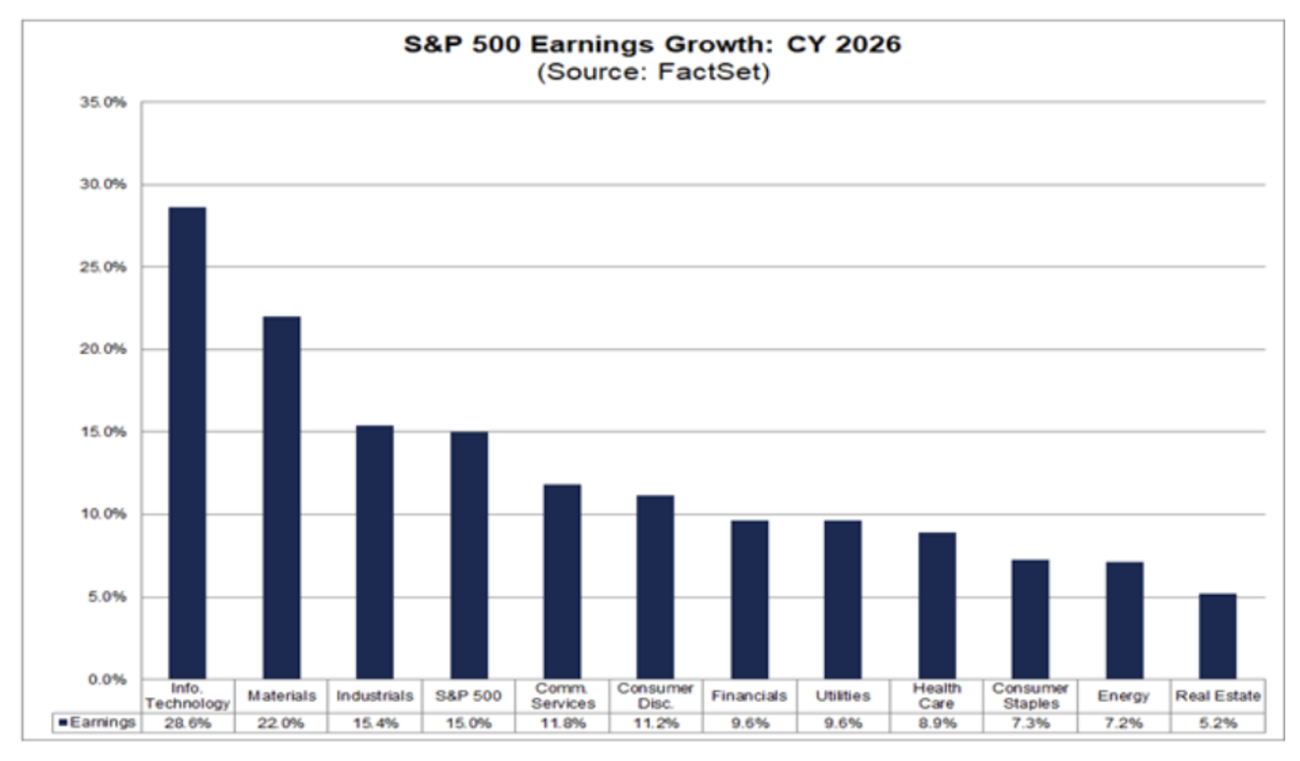
Earnings should be a strong driver of equity returns in 2026. With most analysts projecting 12-15% earnings growth for the S&P 500, earnings growth alone could help move the market to the double-digit return range. Even if valuations were to come in a bit, meaning the multiple paid on earnings (typically expressed as a price-to-earnings multiple) were to compress from 23x to 22x on the S&P 500, 15% earnings growth would still result in a 10% price return. We aim to target our portfolio exposure to higher-growth companies while maintaining a quality tilt to our stock exposure (strong earnings, positive cash flow, and low debt), as we believe high-quality companies will outperform the broader market this year. The technology sector is expected to maintain the highest earnings growth in 2026, but we expect to be well diversified among other high-growth sectors and industries as well.
Stock Buybacks
Stock buybacks are set to surge in 2026, and the additional buying pressure should promote higher stock prices. $1.1 trillion in buybacks are expected from S&P 500 companies as cash flows remain healthy and boards are driven to reward shareholders. $1.1 trillion represents almost 2% of the total S&P 500 market capitalization, so if we see that level of buyback activity, returns could be boosted by roughly that 2% throughout this year.
Deregulation
Lower taxes and regulatory burdens should provide another tailwind to markets in 2026. US officials estimate that cost savings from deregulation could add 30-50bps (0.3-0.5%) to GDP growth annually. The current administration is pursuing a 10-to-1 Deregulation Initiative to significantly reduce onerous regulations on companies and individuals. This will be particularly impactful for the Financials, Housing, and Energy industries. While much of the deregulatory benefit is attributed to the corporate earnings growth figures mentioned above, the impact on investors is notable as well. Tax refunds are set to be higher than normal, providing more cash buying power for investors.
Market Breadth & Sector Rotation
Over the past few years, market breadth has been at record lows – starting with the Mag 7 and evolving into a smaller handful of mega-cap companies driving most market returns. Starting in 2025, we saw market performance begin to broaden out, with more and more smaller companies participating in both earnings and price returns.
As we enter 2026, we expect this trend to continue due to several factors.
- Lower rates will help small & mid-cap businesses more than larger companies. As discussed in previous newsletters, this dynamic will continue to play out, as “smid” caps are more reliant on debt.
- Many small and mid-cap companies have increased their earnings faster than their stock price in the last few years, leading to relatively low Price/Earnings ratios, or “cheaper.”
- Deregulation generally helps smaller companies the most. While most large-cap companies have teams of lawyers to help them stay compliant, small-cap companies bear the regulatory burden the most.
With lower interest rates and further deregulation expected in ’26, we expect continued broadening of returns.
Beyond AI – Other Sectors We Favor
Companies linked to artificial intelligence aren’t the only ones we believe will excel in 2026. Other industries we favor this year include banking, asset management, aerospace and defense, robotics, and biotechnology. Each of these industries has unique tailwinds that we believe will help them outperform in the coming year.
Banking and M&A
As Fed policy rates continue to drift downward, it should help the broad financial sector by creating a more “normal” upward-sloping yield curve. Banks should benefit by lending out dollars at higher rates while providing lower yields on deposits and overnight loans, creating positive momentum for net interest income. Lower rates should also help drive investment banking revenues via higher corporate loan issuance and a more active mergers and acquisitions (M&A) environment. We also favor asset and wealth managers who should benefit from recent market growth and trading activity, helping to drive their profits higher. We prefer large banks that are less exposed to consumer loans and more exposed to commercial and investment banking. Big banks had a strong 2025, and we expect this performance to continue in 2026 as well.
Defense
Aerospace & Defense is an interesting industry from an investment perspective, particularly given recent overseas wars, which have driven innovation and renewed government spending. With a potential wind-down in tensions from a conclusion of the Israel-Iran conflict and a potential cessation of the Ukraine-Russia conflict, defense spending may be affected. However, we still expect US rearmament and European ramp-up to drive positive incremental growth over the next 12-36 months.
Industrials
Industrials have gained market attention over the past year, mainly due to the repatriation of production. Growth in domestic manufacturing not only means more production, but a demand for industrial labor and efficiency, which is further driving demand for advanced robotics (and thus advanced components such as bespoke actuators)
Healthcare/Biotech
Healthcare companies remain an area of interest, as discussed in previous newsletters. Due to an aging population, people are living longer, therefore consuming more healthcare in the form of diagnostics, artificial joints, and advanced life care services. Biotech companies traditionally rely heavily on debt financing until new drugs reach production and profitability. With the downward trajectory in rates, debt burdens are set to decline. Cheaper financing also boosts acquisition activity, and many small biotech companies are ripe for takeover by their large pharmaceutical counterparts.
Risks to Monitor
While we are generally bullish and expect positive market outcomes in 2026, it is critical to evaluate the risks we are monitoring as we enter the new year.
Tariffs
Tariffs have essentially been baked into the proverbial economic and market “cake” at this point. Turmoil ensued following the early April 2025 announcement, but since then, tariffs have become more moderate, targeted, and accepted by investors. However, an upcoming Supreme Court decision is set to bring tariffs back to the top of Wall Street’s conversation. Depending on how the Supreme Court rules on whether the use of IEEPA was justified in instituting some of the Trump Administration’s tariffs, Tariffs pose a two-way risk. IEEPA is used to justify roughly half of current tariffs, so not all tariffs are at risk, but this still marks a significant percentage.

If the use of IEEPA is rejected, a significant portion of tariff revenue will cease to flow to the U.S. Government. This tariff revenue has improved the debt outlook for the U.S. and is reducing current deficits. U.S. Treasury holders are likely fans of tariffs at this point, as a more balanced budget improves the likelihood of payback in the future. If tariff revenue is removed, fiscal concerns may rise, generating fresh scrutiny about the U.S. debt and deficit, which may ultimately disturb the bond market. If yields rise accordingly, it could negatively impact both bond and stock markets. On the other hand, corporations may look favorably on a ruling against IEEPA tariffs. Removing the associated tax burden would help improve margins on tariff-impacted goods. This creates a mixed reaction function for Wall Street; however, we view a ruling against IEEPA tariffs as a net-negative for markets at this point in the cycle.
K-Shaped Economy
If you’ve been tuned into stock market media, you’ve likely heard about the “K-Shaped Economy.” This refers to the widening wealth gap between U.S. citizens, primarily between those who own and those who do not own investment assets. Particularly since the pandemic, higher-income households and owners of financial assets have seen strong wealth growth while those without assets have seen their standards of living decline due to inflation. If this dynamic continues to exacerbate, it may not have immediate market implications, but it may create political or social unrest, leading to market implications. Household debt is a figure we are watching closely, and while it hasn’t exceeded pre-pandemic levels, debt burdens are increasing, raising some concern about the health of lower-end U.S. consumers.
Valuation Concerns
In 2025, the S&P 500 reached relatively high Price-to-Earnings levels, indicating to some it’s an “expensive” stock market. While multiples have moderated slightly, we’re less concerned for a couple of reasons:
- Historical P/E is based on a different market. When market commentators cite “historical” S&P P/E ratios, they usually use the past 20+ years to calculate an average P/E. The problem is that 20 years ago, the iPhone hadn’t even been released. The stock market was fundamentally different then, so comparing P/E ratios over such a long period is inherently flawed.
- The Stock Market is a “market of stocks” – While the broad S&P 500 P/E may be higher than many are comfortable with, our approach includes investing in mostly individual stocks, as opposed to market-wide (or world-wide), broad exposure ETFs. This means we get to determine whether P/E makes sense at the company level, rather than simply accepting the average.

The AI “Bubble”
Many market commentators (along with a few professional analysts) have expressed concern about the valuation of AI-linked companies and the future prospects of AI; many are trying to equate this to 1999. While we agree that not all AI companies are fairly valued (as noted above, we try to avoid overvalued ones), we see continued AI progress as a real force. As discussed earlier, there are many facets of AI beyond the Large Language Models (LLMs) that made it so popular. From enterprise solutions to powering industrial (and eventually consumer) robotics, we’d argue that AI is here to stay.
Conclusion
We feel confident about the economy and markets heading into 2026. The ongoing AI Supercycle, Federal Reserve rate cuts, strong earnings growth, and other macro factors contribute to a bullish thesis for markets this year. We believe stock and asset class selection will play a vital role as returns and earnings potential continue to broaden across the asset universe, so we look forward to conducting diligent analysis as we construct client portfolios for good outcomes.
While investing never comes without risk, we believe this year’s opportunity is weighted to the upside. Should fundamentals change, we will continue to take an active approach to investment management, making adjustments as warranted by market conditions. We look forward to updating you on our outlook throughout the year via our quarterly newsletters, podcasts, and weekly email notes. From all of us at Beck Capital Management, we wish you and your family the best in 2026 and are looking forward to a happy, healthy, and prosperous year!
Disclosures
This material represents an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions. It should also not be construed as advice meeting the particular investment needs of any investor. Past performance does not guarantee future results.
Nothing contained herein is to be considered a solicitation, research material, an investment recommendation or advice of any kind. The information contained herein may contain information that is subject to change without notice. Any investments or strategies referenced herein do not take into account the investment objectives, financial situation or particular needs of any specific person. Product suitability must be independently determined for each individual investor.